Half a Dozen Analysts Have a Buy Signal on Okta
Wall Street just handed Okta a coordinated vote of confidence tied to one bold bet on AI agents, and the price targets analysts set reveal exactly how high they think this identity play can run.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Wall Street’s tone on Okta (NASDAQ:OKTA | OKTA Price Prediction) turned decisively bullish after Oktane 2026, with six firms lifting price targets while maintaining Buy-equivalent ratings on the identity software leader.
The consensus signal: management’s push to make Okta the identity control plane for AI agents is translating into product traction, partner momentum, and sales-force specialization. For long-term investors, the coordinated upgrades reinforce a rebuilding thesis that now leans heavily on agentic identity as the next growth leg.
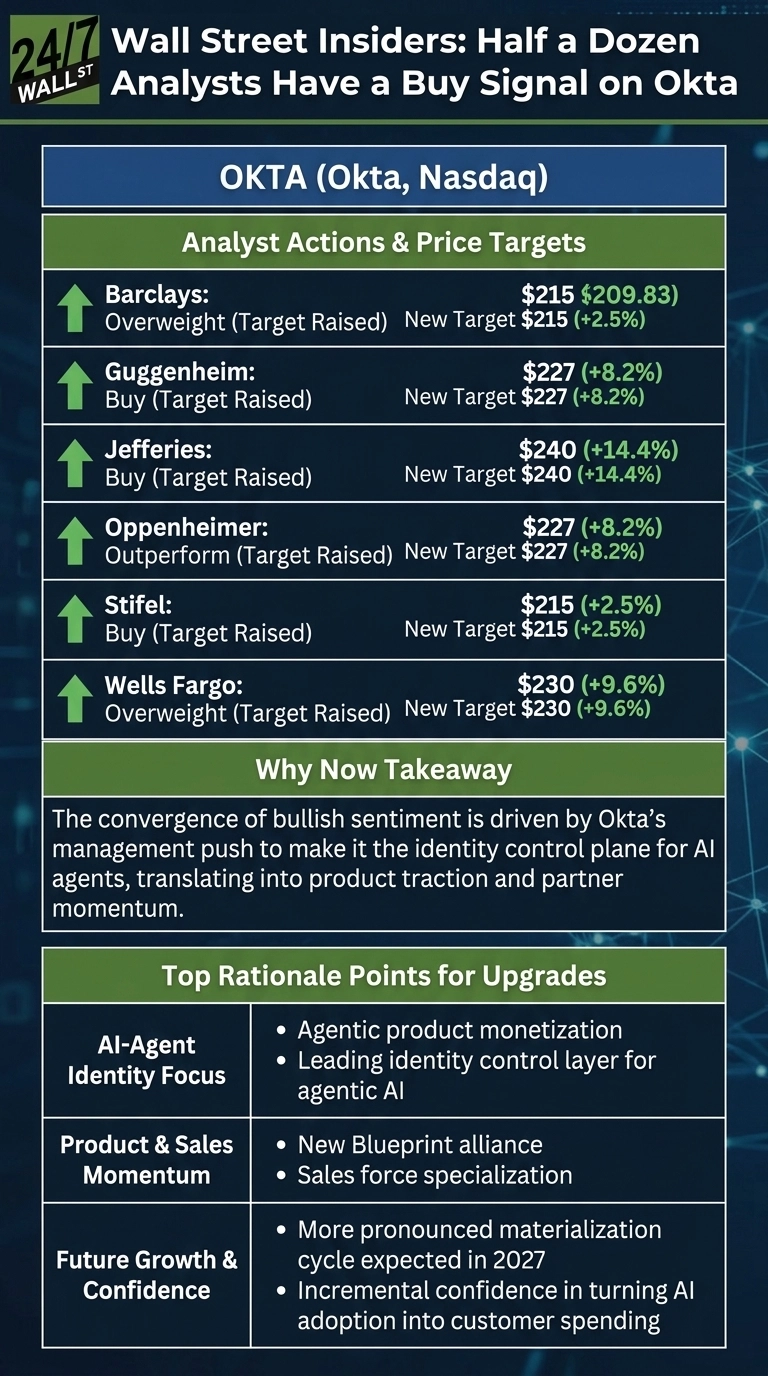
| Ticker | Company | Firm | Action | Old Rating | New Rating | Old Target | New Target |
|---|---|---|---|---|---|---|---|
| OKTA | Okta | Barclays | Price target raised | Overweight | Overweight | $180 | $215 |
| OKTA | Okta | Guggenheim | Price target raised | Buy | Buy | $188 | $227 |
| OKTA | Okta | Jefferies | Price target raised | Buy | Buy | $200 | $240 |
| OKTA | Okta | Oppenheimer | Price target raised | Outperform | Outperform | $190 | $227 |
| OKTA | Okta | Stifel | Price target raised | Buy | Buy | $180 | $215 |
| OKTA | Okta | Wells Fargo | Price target raised | Overweight | Overweight | $200 | $230 |

Analyst Case for Okta Stock
Barclays cited a new Blueprint alliance, agentic product monetization, and sales force specialization as the drivers behind its raise.
Jefferies pointed to channel checks confirming that identity is top of mind for agentic security and expects a “more pronounced” materialization cycle in 2027.
Guggenheim said Okta is backing up its marketing around AI with product that seems to be gaining momentum, while Oppenheimer left the event more confident in Okta as a leading identity control layer for agentic AI.
Wells Fargo came away with incremental confidence in Okta’s ability to turn AI adoption into meaningful incremental customer spending.
Two more firms lifted targets without upgrading. BofA’s Tal Liani raised his target to $220 from $200 at Neutral, calling Oktane “another positive step for Okta’s AI narrative”.
TD Cowen’s Shaul Eyal moved to $200 from $175 at Hold, noting new AI products could become a new entry point for customers into its broader identity platform.
Okta Snapshot Behind the Ratings
Okta carries a market capitalization of roughly $35.07 billion and posted Q2 FY27 as a “record bookings quarter for a non-Q4”. New products contributed approximately 30% of bookings, and the company now serves over 600 customers with greater than $1 million in ACV.
Management guided FY27 revenue growth of 10% to 11% with a non-GAAP operating margin of 26% and free cash flow margin of 28% to 29%. Analyst coverage is broad, with 26 Buy ratings, 9 Strong Buys, and 9 Holds.

Why the Move Matters Now
Okta stock has advanced 142.66% year to date and 60.21% over the past month, closing in on a 52-week high of $207.20.
That rally has stretched valuation to a forward P/E near 52x, so the raised targets matter: they justify multiple expansion with a credible AI-agent identity narrative rather than pure momentum.
Jefferies’ $240 target sits at the high end of the group, while Barclays and Stifel anchor the low end at $215. Estimate revisions confirm the tone, with 42 upward EPS revisions and zero downward revisions for FY27 over the trailing 30 days.

Portfolio Takeaway for Retirement Investors
Six Buy-side price target hikes signal that Wall Street sees Okta’s agentic identity opportunity as durable. Management itself calls AI contribution “immaterial” for FY27, meaning much of today’s price already reflects future execution.
Retirement-focused investors weighing the analyst upgrade cycle should size positions with that gap in mind, watching FY28 conversion of the AI pipeline as the key proof point.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.