DraftKings Just Became a Show-Me Stock. Holders Have One Move
UBS, JPMorgan and Stifel downgraded DraftKings on Monday, one trading day after the stock fell 21% on its third-quarter report and guidance cut. Here is what the three notes said, what Friday cost per 1,000 shares, and a sell, hold…

DraftKings just became a show-me stock, in Stifel’s words, and the one move for a holder that costs least is to book the loss now, by selling or trimming, and let the next quarter’s numbers decide whether to buy back. UBS, JPMorgan and Stifel each downgraded the stock before Monday’s open, one trading day after it fell 21% to $18.51 on its third-quarter report. The three new price targets sit between $21 and $22, down from an average of about $37.
If you hold DraftKings (NASDAQ: DKNG), here is our view in plain words. Stifel called it a “show-me story,” and holding it means you wait several quarters for proof that its prediction-markets spending pays off under rules a court may still rewrite. If you are sitting on a loss in a taxable account, booking that loss now costs you least, and the tax code gives you a 30-day window to change your mind.
Three downgrades in one morning are a signal that Wall Street has pulled its benefit of the doubt from DraftKings for the next several quarters, and that the stock now has to prove itself with results. They are also three opinions among 37: 31 analysts still rate the stock Buy or Strong Buy, according to Koyfin, with an average 12-month target of $31.17, about 68% above Friday’s close.
What happened
DraftKings reported Thursday evening. Revenue was $1.33 billion, up 16% from a year earlier. Adjusted EBITDA was a loss of about $317 million. The company cut its 2026 adjusted EBITDA guidance to $175 million to $275 million from $700 million to $900 million, a 72% cut at the midpoint, to pay for $650 million to $700 million of spending this year on Predictions, its event-contracts business. For 2027 it guided to adjusted EBITDA of $800 million to $1 billion, with another $250 million to $350 million going into Predictions.
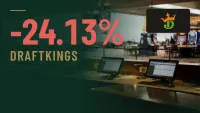
Friday, the stock opened down and touched $16.55, 29.6% below Thursday’s close, before finishing at $18.51, down 21.3%. It was the worst day since November 2022, and about $2.5 billion of market value was gone by the close. Per 1,000 shares, Friday cost $5,010. The stock is now down 46% for the year and 49% below its Jan. 5 closing high of $36.24.
What the analysts said
JPMorgan’s Daniel Politzer cut the stock to Neutral from Overweight and his target to $21 from $30, removed it from the firm’s Analyst Focus List, and wrote that it is “increasingly difficult to recommend the stock,” with little conviction in the company’s 2027 and 2028 EBITDA.
UBS’s Robin Farley went to Neutral from Buy and cut her target to $22 from $48. She said it is difficult to assign meaningful value to the prediction-markets business given the regulatory outlook.
Stifel’s Jeffrey Stantial moved to Hold from Buy, target $21 from $32. He called the Predictions investment strategically sound, said the optics are challenging, and noted that DraftKings has missed its initial full-year guidance three years in a row.
Read the targets as a sentence. A $21 target is 13.5% above Friday’s close and $22 is 18.9% above it. A Neutral rating with that much room says the fall has already happened, and so has the reason to own the stock.
What it means for a holder this week
Say you bought 1,000 shares at the Dec. 31 close of $34.46, a $34,460 position inside a $1,100,000 taxable brokerage account. At Friday’s close your shares are worth $18,510, a loss of $15,950, or 46%, and the position is 1.7% of the account. If the stock reaches the new $21 targets, you hold $21,000, still $13,460 under your cost. Even the Koyfin average target of $31.17 leaves you $3,290 short. Getting back to even from $18.51 takes an 86% rise.
What moves your shares now is the rest of the sell side catching up (BofA, Macquarie and Truist cut targets while keeping Buy ratings) and the regulatory debate over sports event contracts. Management’s base case is a Supreme Court ruling in mid-2028 and says its 2026 Predictions customers pay back in about 20 months. Give the other side its due: sportsbook net revenue grew 36%, monthly unique payers rose 13% to 4.1 million, and the company holds $1.1 billion in cash. CEO Jason Robins said the company is “set up for an exceptional 2027.”
Sell, hold or trim
Sell if you bought DraftKings for the profit story it was telling in August, when 2026 adjusted EBITDA was guided at $700 million to $900 million. The company you bought changed on Thursday night. The $575 million taken out of the midpoint went to a business whose legal footing is in dispute.
Hold only if you believe Predictions survives and you are willing to wait to be paid. The payoff, by management’s own schedule, is 2027 and 2028.
Trim if you cannot decide. Selling 500 of your 1,000 shares at $18.51 raises $9,255, books a $7,975 loss, and keeps $9,255 in the stock.
The tax angle favors acting if your shares sit in a taxable account. A loss on shares you bought this year is short-term. It offsets your capital gains dollar for dollar, then up to $3,000 a year of ordinary income, with the rest carried forward (IRS Topic 409). A $15,950 loss with no gains to offset takes you five full years plus $950 to use; against gains taxed at 15% it is worth $2,392 at once. If you sell and buy DraftKings back within 30 days before or after, the wash-sale rule disallows the loss and adds it to the cost of your new shares, so if you still believe, wait 31 days or accept that. In an IRA you have no loss to harvest, and the decision is purely about the business.
The bottom line
Three downgrades, targets of $21 to $22, and a stock 46% down for the year. The 31 remaining Buy ratings are the lagging indicator here, with an average target 68% above the price. DraftKings has become a show-me stock. If you hold it with a short-term loss, the clearest move this week is to sell or trim, book the loss, and decide about buying back after 30 days with the next quarter’s numbers in hand.
Contact [email protected] for any questions or corrections.
I've been writing about stocks and personal finance for 20+ years. I believe all great companies are tech companies in the long run, and I invest accordingly.